Rates & Costs
Why Did My Florida Mortgage Payment Go Up?

Your Florida mortgage payment may go up because the property was reassessed after the purchase, causing the tax bill and monthly escrow amount to increase. If the original escrow estimate was too low, your payment may also include repayment of the resulting shortage.
Find Out What Part of the Payment Changed
When people say their mortgage went up, the loan itself may not have changed.
Your principal and interest could be exactly what you agreed to at closing. The increase may be coming from property taxes, homeowners insurance, mortgage insurance, or an escrow shortage.
For most borrowers, the total monthly payment includes more than principal and interest. It may also include taxes and insurance collected through an escrow account, as the Consumer Financial Protection Bureau explains. (consumerfinance.gov)
Escrow means your mortgage servicer collects part of those yearly expenses each month. The servicer then uses the account to pay the bills when they come due. Taxes and insurance premiums can change from year to year, which means the escrow portion of your payment can change too. The CFPB provides a plain-English explanation of escrow accounts here. (consumerfinance.gov)
Start by comparing your original payment breakdown with your latest statement. Don’t look only at the total.
Review these lines one at a time:
- Principal
- Interest
- Property taxes
- Homeowners insurance
- Mortgage insurance, if applicable
- Escrow shortage repayment
That comparison tells you whether the change came from the loan or from the ongoing cost of owning the home.
Why the Seller’s Property Tax Bill Can Be Misleading
You find a Florida home online and see what the seller paid in property taxes last year.
You divide that number by 12 and add it to your estimated payment.
It seems reasonable.
Here’s the part nobody tells you. That tax bill may reflect the seller’s assessed value, exemptions, and years of accumulated tax benefits. It may have very little to do with what you will owe after buying the home.
One important benefit is Florida’s Save Our Homes assessment limitation. Once an eligible homestead is established, Save Our Homes limits annual increases in assessed value to 3% or the change in the Consumer Price Index, whichever is lower.
Over time, that can create a large difference between the property’s current market value and its assessed value.
When ownership changes, a homestead property generally loses the prior owner’s Save Our Homes benefit and becomes subject to assessment at just value on the following January 1. The Florida Department of Revenue’s Save Our Homes guide explains the reassessment and portability rules. (floridarevenue.com)
That’s why a seller’s tax bill can look unusually low compared with what a new owner may owe.
Treat the seller’s property tax bill as a clue, not a quote.
Why the Timing Creates a Delayed Surprise
Florida property is assessed as of January 1 each year. When you buy during the year, the tax information available at closing may still reflect the previous owner’s situation.
The first year can look normal.
The surprise may come after the next January 1 assessment.
The Florida Department of Revenue explains that property appraisers assess property at just value each January 1 and that newly acquired real property is generally assessed at just value. (floridarevenue.com)
If the property becomes your permanent residence and you meet the requirements, you may apply for your own homestead exemption through the county property appraiser. Your exemptions and assessment benefits are based on your eligibility, not the seller’s.
A generic online estimate may not account for that reset. Multiplying the purchase price by a general tax rate may also miss exemptions, assessment limitations, portability, and location-specific taxing authorities.
How One Tax Bill Went From $2,500 to Over $10,000
I had a closing where the prior owner’s annual property tax bill was approximately $2,500.
That owner had a special 100% property tax exemption. The new owner did not qualify for the same exemption.
Once the property was evaluated based on the exemptions available to the new owner, the annual bill increased to more than $10,000.
That’s an extreme case, but it shows why copying a seller’s tax bill into your budget can be dangerous. The $2,500 figure described the seller’s situation, not the buyer’s future tax obligation.
Florida has different exemptions and tax benefits based on the property and owner. A buyer’s potential tax bill can depend on questions such as:
- Will the property be a primary residence, second home, or investment property?
- Is the buyer moving from another Florida homestead?
- Could the buyer qualify for portability?
- What exemptions currently appear on the property record?
- When did the current owner purchase the home?
Two people buying the same property could have different tax outcomes because their exemptions and portability situations may differ.
How Portability Can Affect the Estimate
Portability may allow an eligible Florida homeowner to transfer some or all of the Save Our Homes assessment difference from a previous homestead to a new one.
It doesn’t happen automatically. The homeowner must qualify and apply within the required period.
According to the Florida Department of Revenue, eligible homeowners generally file for portability with the county property appraiser by March 1 of the first year after moving. (floridarevenue.com)
If you think portability may apply, estimate it separately using information from the property appraiser. Don’t assume the new property will receive the same tax treatment as your old home or the seller’s home.
Why an Escrow Shortage Makes the Increase Feel Bigger
Suppose your servicer collected escrow based on a property tax estimate that turned out to be too low.
When the actual bill arrives, the servicer may pay it from your escrow account. But the account may no longer have enough money to maintain its required balance.
That creates an escrow shortage.
The servicer then performs an escrow analysis. This is an accounting review used to project the next year’s expenses and determine whether the account has a shortage, surplus, or deficiency. Federal escrow rules and explanations are available from the CFPB. (consumerfinance.gov)
Your payment can then increase for two separate reasons:
- Higher ongoing taxes: The servicer needs to collect enough each month to cover the new annual bill.
- Shortage repayment: The servicer may collect additional money to make up for the amount missing under the old estimate.
You’re paying toward the higher future bill while catching up on the previous shortage.
That’s why the adjustment can feel much larger than expected. Your annual escrow statement should show the account history, projected expenses, and how any shortage is being handled.
How to Estimate Florida Property Taxes Before Buying
Don’t rely on a county average.
A property may be affected by rates and assessments from the county, school board, city, and special districts. Two similar homes can have different tax bills based on their exact locations.
Instead, research the individual property.
1. Look up the exact address
Go to the county property appraiser’s website and search for the property.
2. Review the three property values
Look for:
- Just value: The property appraiser’s market value
- Assessed value: The value after applicable assessment limitations
- Taxable value: The assessed value after exemptions
The Florida Department of Revenue outlines how these values work together. (floridarevenue.com)
3. Check the current exemptions
Identify every exemption shown on the property record. Don’t assume those exemptions will transfer to you.
4. Find the seller’s purchase date
A longtime owner may have accumulated a substantial Save Our Homes assessment difference. That can make the existing bill less useful when estimating a new owner’s taxes.
5. Use the county’s buyer estimator
If the county property appraiser provides a buyer or tax estimator, enter the expected purchase information and read its assumptions carefully.
Don’t automatically carry over the seller’s exemptions or Save Our Homes benefit.
6. Estimate portability separately
If you’re moving from another Florida homestead, ask the property appraiser how portability may apply to your situation.
7. Build the full housing payment
Combine the property tax estimate with:
- Principal and interest
- Homeowners insurance
- Mortgage insurance, if applicable
- Homeowners association charges, if applicable
- Other property-related costs
The price you can get approved for and the price you can live with comfortably are two different numbers. You need the full payment before you can compare them.
Bottom Line
A Florida mortgage payment can jump when the home is reassessed after the purchase, the seller’s exemptions no longer apply, and the escrow account must collect both higher ongoing taxes and a shortage.
Checking the exact address, ownership history, exemptions, intended occupancy, and possible portability gives you a more useful estimate before you make an offer. Those numbers can then be combined with insurance and the actual loan structure to help you understand the full housing payment.
Get the Numbers Before You Buy
If you’re still working out the payment you can comfortably carry, the next step is to use tools that help organize the full picture or talk through the specific property and loan file.
Frequently asked questions
Why did my mortgage payment increase if I have a fixed-rate loan? +
A fixed interest rate generally keeps the principal-and-interest portion stable, but the total payment may still change. Property taxes, homeowners insurance, mortgage insurance, and escrow shortage repayments can increase the amount due each month.
Do Florida property taxes increase after buying a home? +
They can. A change in ownership generally causes the prior owner’s Save Our Homes benefit to be removed, with the property subject to assessment at just value on the following January 1.
Can I use the seller’s property tax bill to estimate my payment? +
Use it as background information, not as your final estimate. The seller may have exemptions or assessment benefits that will not transfer to you.
What is an escrow shortage? +
An escrow shortage occurs when the account balance is below the amount the servicer projects it will need. Your payment may increase to fund the new tax or insurance amount and repay the shortage.
How can I estimate taxes before buying a Florida home? +
Look up the exact address on the county property appraiser’s website and review its just, assessed, and taxable values. Check the current exemptions, use the county’s buyer estimator when available, and evaluate any possible portability separately.
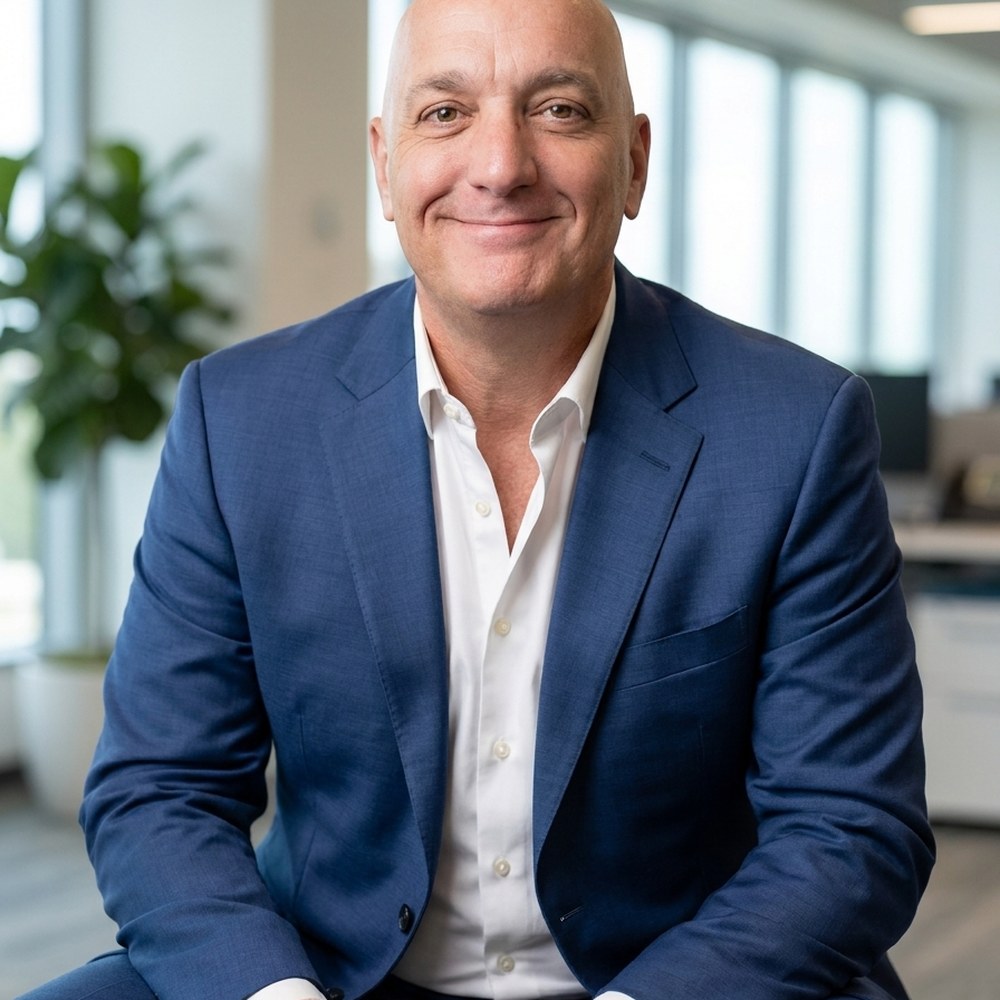
About the author
Emmett Dempsey — Mortgage Broker / Owner
NMLS #208522
I'm Emmett Dempsey, a U.S. Army veteran, a Certified Mortgage Advisor, and the owner of Treasure Coast Mortgage, a veteran-owned brokerage here in Port St. Lucie. Credentials: NMLS #208522; Treasure Coast Mortgage, LLC, NMLS #1958997; Certified Mortgage Advisor Expertise: VA, Reverse, FHA, Conventional, Non-QM. Helping Home buyers and homeowners accomplish their goals.
More about Emmett →Ready to talk numbers?
Schedule a 15-minute call. We'll walk through your situation and show you what's actually possible — no pressure, no pitch.
Book a call

